The short answer
Home insurance can cover a garage roof hit by a named peril such as a storm, subject to the terms of your policy. It rarely pays for gradual deterioration, poor upkeep or a roof that was already failing. Attached and detached garages can be handled differently, so check the buildings section, and keep photographs and a roofer's report.
What insurers usually pay for
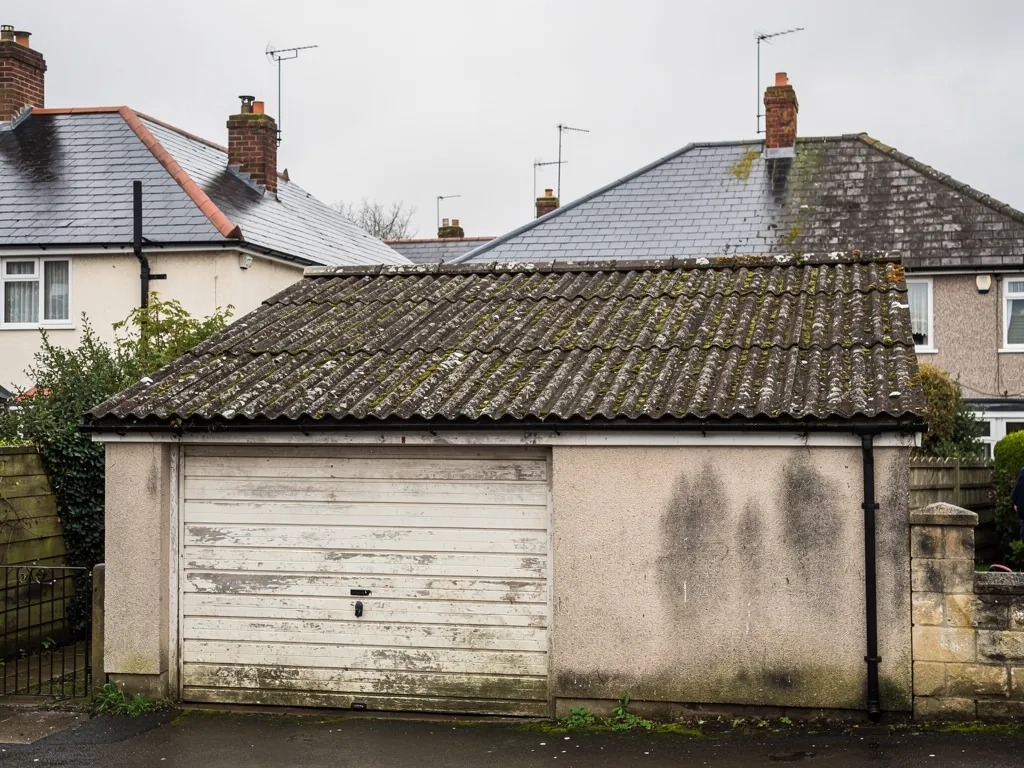
Buildings insurance is written around events: a gale, a fire, a falling branch, an impact. If one of those wrecks a garage roof, the repair may fall within cover, depending on the terms. What a policy does not do is keep a roof in good order. Damage that creeps up slowly, such as a covering that has perished or sheets that have cracked with age, is commonly classed as wear, which is excluded.
Which? reported in November 2025 that ordinary policies may refuse damage traced to poor maintenance, with water getting in through a neglected roof given as the example. Quoting Financial Conduct Authority data, it also said that just 32 per cent of storm claims made in 2024 ended in a payout. That figure cannot predict your outcome, but it shows why wording and evidence count.
Nothing here guarantees that a claim will go through, and we do not act for customers in dealing with insurers. What we can describe is the difference between a roof hurt by weather and a roof worn out by years.
Attached and detached garages
Where the garage stands can change how it is treated. A garage built into the house, or joined to it, is normally part of the main building. A detached garage is often named separately in the policy as an outbuilding, and some policies set different limits or conditions for outbuildings. A few restrict certain constructions or old coverings, so the details are worth reading.
Look in the buildings section of your schedule and policy booklet for the words garage, outbuilding and detached. If you cannot tell whether the garage is included, ask the insurer or broker to confirm in writing rather than assume. Flats and shared garage blocks may be insured under the block policy instead, and the freeholder or managing agent can tell you.
An unusual roof, such as cement sheet that might contain asbestos, is also worth mentioning to your insurer. Our note on removing an asbestos garage roof yourself explains why disturbing such sheets without a plan carries a hazard of its own.
Policies also differ on what counts as a garage. A lean-to store, a car port or a timber shed with a felt roof may be treated as a contents item or left out of cover completely, and a garage that has been converted to living space can fall under different rules again. If your use of the building has changed since the policy began, tell the insurer, because an out-of-date description is a common reason for trouble at claim time.
How a storm gets defined
A number of insurers follow the Association of British Insurers wording for a storm, which includes gusts of 55 mph or more. That line is one reason a claim after an ordinary windy night can be disputed. The insurer may pull weather records for your postcode on the date, and if the wind never reached the stated level they may say the roof's condition was to blame.
One Financial Ombudsman Service case turned on this very point. The ombudsman weighed weather reports from the area instead of a single gust figure, decided wind was the main reason the tiles had gone, and read the wear exclusion in that particular policy as applying only to accidental harm. A different policy or different facts could go the other way, so it is an illustration, not a rule.
Should a decision seem wrong, ask the insurer to explain it in writing and then look at the complaints route. The Ombudsman's website sets out how, and the ABI pages explain common terms.
Evidence that helps
Good evidence makes any claim easier to assess. Before tidying up, take dated photographs of the roof, of sheets or tiles on the ground and of any marks inside. Jot down the date you spotted the problem and the conditions outside that week. Keep fallen pieces unless they might be asbestos, in which case leave them where they lie and say so when you report it.
A roofer's report adds weight because it can name the cause and the extent in ordinary language. A report that says a sheet was lifted off by the wind at a sound fixing reads very differently from one that says the fixings had rusted through. Be ready for questions about the roof's age and upkeep, and answer them truthfully.
Insurers generally expect you to limit further harm. A temporary cover over an opening, or a make-safe by a roofer, is normally sensible and should be documented with receipts. If the repair would also change the garage roof's height or shape, see our page on garage roof planning permission before agreeing the scope.
Where we fit in
We can survey a damaged garage roof, tell you what we find, and set the repair or replacement out in a written fixed price. We give leaks and storm damage priority, and a roof standing open to rain is made safe before anything else, ahead of any longer-term work. Whether your claim is paid is between you and the insurer.
If the insurer agrees to pay, ask whether it will fund a like-for-like covering or allow an upgrade at your own cost. Some roofs, such as box profile roof sheets, are straightforward to match, while an old cement sheet roof is a more complicated case. Agree the scope with the insurer before work starts, since paying first and claiming later leaves less room to argue.
Anything we install is covered by a ten-year workmanship guarantee in writing, which is a separate matter from your home policy. The wider picture on garage roofs, from materials to clearing the site, is under garage roof replacement.