The short answer
Insurance may pay for ridge tiles blown off in a storm, but it depends on your policy and on whether the wind or poor condition caused the loss. Many insurers use a storm threshold of gusts of at least 55 mph and exclude wear and tear, so tiles on weak, old mortar can be refused. Photographs and a roofer's written report give a claim its best chance.
How insurers treat storm damage to a roof
Buildings insurance usually covers damage from a storm, and a roof that loses tiles in a gale looks like the obvious case. The difficulty is in the definition and the cause.
Many insurers follow the Association of British Insurers' idea of a storm, where gusts reach at least 55 mph. A blustery day that did not reach that level may not count, even though a loose ridge tile can come down in less. Wear and tear is commonly excluded as well, for instance rain entering a roof that has been left to deteriorate.
The numbers show how often claims fail. Which? reported on 20 November 2025, citing figures from the Financial Conduct Authority, that only 32% of storm-related claims made in 2024 resulted in a payout. That does not tell you why the rest failed, since many may never have been valid claims, but it is a reminder that a storm event on its own does not guarantee payment. Policies differ, and the wording of yours is what counts.
The problem of mortar that was already weak
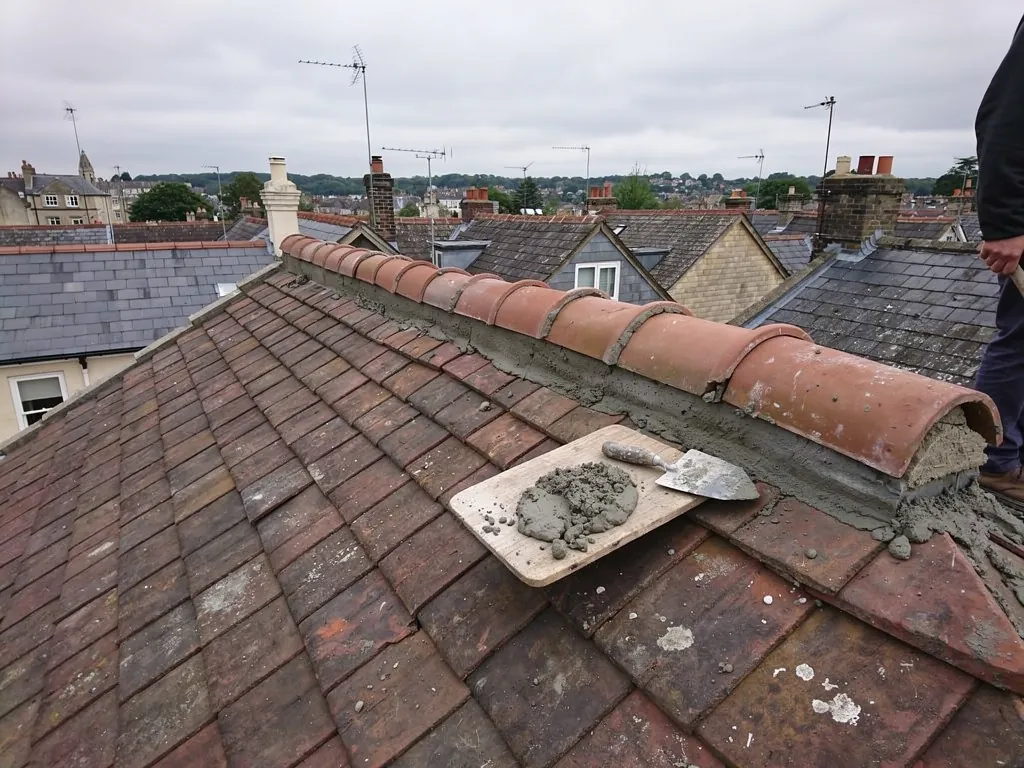
Ridge tiles are the commonest place for this argument. A tile bedded on sound mortar and fixed down will rarely leave the roof except in a severe event. A tile on cracked, crumbling mortar can come off in a strong wind, and the insurer may argue that age had done most of the work already.
From their side, the logic is simple: the policy covers sudden damage, not the slow decay of a building. If a loss adjuster sees dry, sandy mortar still stuck to the underside of a fallen tile, or a long-open crack along the ridge, they may conclude the failure came from wear and tear.
From yours, the question is what actually caused the tiles to come off. The Financial Ombudsman Service published a case where tiles came off in wind. Lacking a wind-speed reading, the ombudsman turned to the local weather reports, decided wind was the main cause, and observed that the policy's wear exclusion covered only accidental damage. Every case turns on its own facts, yet it shows an insurer's first answer is not necessarily final.
See our page on verge repair for the same issue at a gable edge, where mortar and wind work together in the same way.
Evidence that helps a claim
The best time to gather evidence is before anything is repaired. Take pictures of the damage standing on the ground and, if safe, at an upstairs window. Take wider shots showing where the tiles landed and the state of nearby roofs and fences, since a pattern of storm damage in the street supports your case.
Keep any fallen tiles, and do not clear up mortar until you have photographed it. Note the date of the weather event, and keep a copy of the local forecast or any weather warning. Check the policy wording for the storm definition, the excess and any exclusions.
A roofer's written report helps too. It should record what is missing, how the rest of the ridge looks, and what the roofer believes caused the failure. A survey from us can describe what is found and illustrate it with pictures, but the claim itself is yours to make, and no report can guarantee an insurer's acceptance. Decisions rest with your insurer and, if you dispute one, with the Financial Ombudsman Service.
Making the roof safe while you wait
Do not wait for the insurer before making the roof safe. Most policies expect sensible action to stop things getting worse, and leaving a hole in the ridge can lead to a second, avoidable loss that the insurer may not cover.
A temporary repair is not the same as the permanent one. Where tiles are down, we prioritise storm damage and make the roof safe first, which can mean covering the gap or refixing what can be refixed. That protects the timbers and the loft while the claim is assessed. Keep every receipt and photograph the work, and tell your insurer what you plan to do before you do it, where you can.
Permanent repair usually means re-bedding the affected length with mechanical fixings, as set out in our page on dry ridge and Building Regulations, where the question of notifiable work is answered. For older and listed houses, some insurers will expect the repair to match the original, which links to our answer on dry ridge on a listed building.
Reducing the chance of a refusal next time
The most reliable protection against a refused claim is a ridge that is in good order. A short check from the ground each year, and after any severe storm, catches cracks and shifted tiles early. Repairs made promptly are cheaper than those made after a loss, and they leave a record that the roof was maintained.
If your ridge is old and bedded only in mortar, having it re-bedded with mechanical fixings brings it into line with BS 5534:2014 and makes the next gale less likely to take a tile. It is also worth reading your policy for the storm definition and the maintenance conditions, and for what you must do after a loss.
Our survey costs nothing and our price, once given, is fixed and written down; the repair then carries a 10-year workmanship guarantee. You can read about related ridge work under ridge and verge repairs. The Which? and Financial Ombudsman Service websites also have plain-English guidance on storm claims, including how complaints about refusals are handled.