The short answer
Home insurance may cover slates lost in a genuine storm, but not if the policy excludes wear and tear and the insurer finds the nails had rusted away. A common insurer test for a storm is a gust of 55 mph or more. Photographs, dates, weather records and a roofer's report on the cause of failure all help, though no claim is certain to succeed.
How insurers define a storm
Policies differ, and your own wording is the document that counts. Even so, the storm definition from the Association of British Insurers, which many insurers apply, starts at gusts of 55 mph. A calmer day gives the insurer room to argue that no storm occurred.
Which? reported in November 2025 that, on Financial Conduct Authority figures, just 32 per cent of storm claims made in 2024 were paid. The figure spans every kind of storm claim, not slate roofs alone, yet it shows that a storm on the news is no guarantee of a settlement.
The point to hold on to is that the insurer pays for damage the policy covers. Whether the slates were lost to wind, or the wind merely found a weakness that already existed, is the question every assessor asks.
Wind damage versus nail sickness
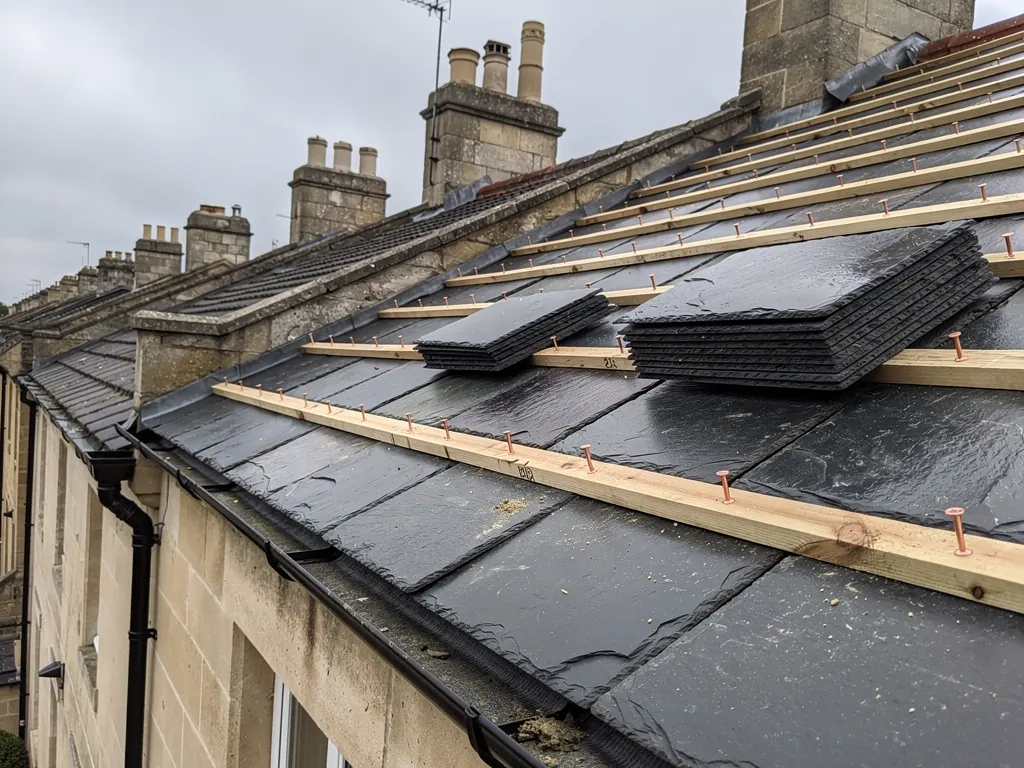
This distinction decides many slate claims. Slates held by sound nails and sound battens can resist strong winds, and when they do blow off, the cause is clearly the weather. Slates on rusted nails may slide out in a moderate blow, and the insurer can claim the roof was failing already.
Nail sickness is the trade term for iron nails corroding and letting slates slip. It is a condition that develops over many years, which is why it sits closer to wear and tear than to a sudden event. Ordinary policies can exclude wear and tear, and the article's example is water that came in through a badly maintained roof.
The evidence on the roof can point either way. Slates that are broken, with sound nails still in the battens, suggest force. Slates that slid out with corroded nail stubs suggest age. Our page on slipped slates shows what to look for.
What a Financial Ombudsman case shows
One published Financial Ombudsman case concerns a refused roof claim. Instead of leaning on a wind-speed figure, the ombudsman read local weather reports, found wind to be the main cause of the tiles being lost, and noted that in that policy the wear-and-tear exclusion reached only accidental damage.
This is one case, and it does not mean your claim will go the same way. It does show that an insurer's refusal can be challenged, and that the cause of damage is a matter of evidence. If a claim is refused, the insurer must explain why, and you can complain, and in time take it to the ombudsman. The service is at financial-ombudsman.org.uk.
We are roofers, not insurance advisers, so the claim is yours to make with your insurer. What we can put in your hands is a clear account of what we find on your roof, with photographs.
Evidence that helps a claim
Evidence is the part you can control. Before anything is moved or mended, gather the following, as far as safety allows.
- Photograph the damage from the ground, from windows and from the garden, including any slates that have landed on the ground.
- Keep the broken slates. Their condition, and the nail holes, show whether they failed by force or by age.
- Note the date and time of the storm, and keep a record of weather reports for your area.
- Get a written roofer's report on the cause, with photographs of the nails and battens.
- Keep receipts for emergency work done to stop further damage.
Do not climb on the roof to take pictures. Slate is slippery and cracks underfoot, so leave the climbing to a roofer. Why slate cracks is set out separately.
Making the roof safe, and what happens next
Policies commonly expect you to limit further damage, and a temporary repair normally counts as that. When water is coming in, stopping it comes first, which is why we put leaks and storm damage first. It might mean a temporary cover, or a few replacement slates so water stops coming in.
Photographs taken at that stage record how the roof looked, so the insurer can see what you found. Keep the roofer's invoice and any report.
Once the roof is dry, the wider question is whether to patch or renew. If the survey shows widespread nail sickness, a few replaced slates will not stop the next storm from taking more, and the sensible route may be a re-slate. Insurers may cover only the storm-damaged part, so it is worth separating the two in the quote. Typical UK ranges for storm-damage fixes are £500 to £1,500 according to MyBuilder's 2026 guide, though your own price follows a survey.
If the roof is old, listed or in a conservation area
An older roof raises more questions. The insurer may ask when it was last maintained, and an assessor may note the age of the slate and its fixings. Keep records of any repairs, and ask your roofer to note the condition of the roof when you have work done.
Listed buildings and conservation-area roofs bring limits on materials, even after a storm. The page on swapping Welsh slate for Spanish explains why the council may want a particular slate, and the insurer's offer may not cover a more expensive match unless the policy says so. Read the wording on that point before you accept a settlement.
Reclaimed slate can sometimes give a good match, and the reclaimed slate page covers it. Our slate roofing service page has the wider picture.