The short answer
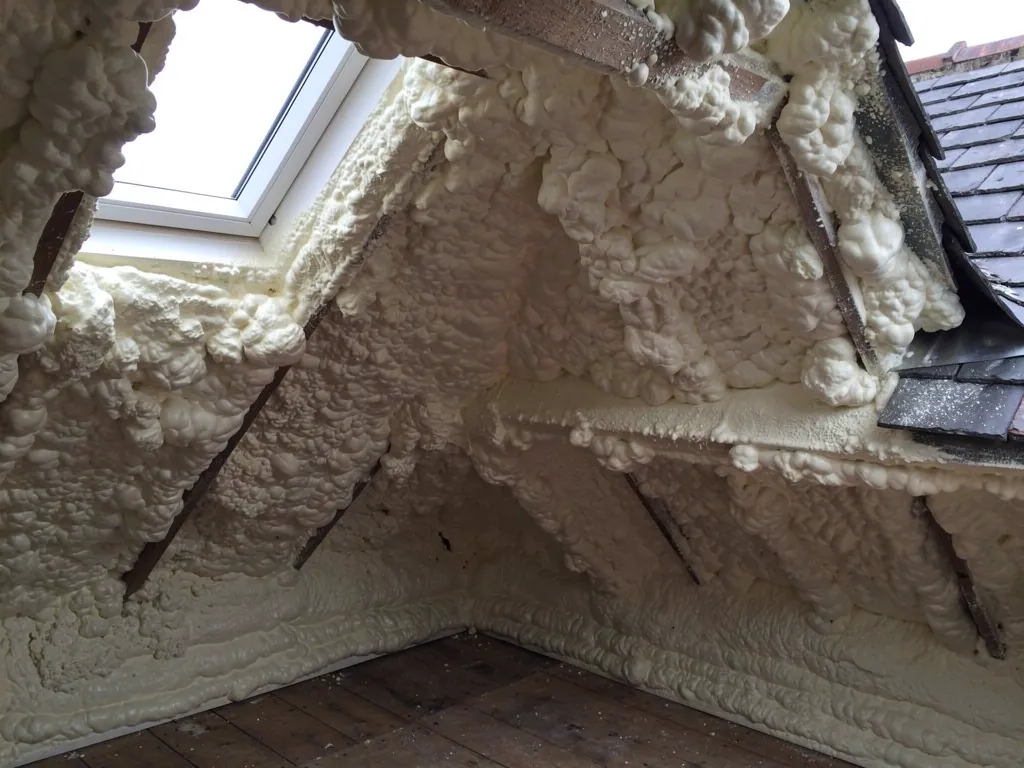
Spray foam can affect home insurance, and you should declare it to your insurer or broker. Insurers differ, and some may ask questions, add conditions or price the risk differently. We cannot say what any insurer will do. Telling them avoids the risk of a claim being disputed later, and a roof report can help.
Why insurers care about foam
Home insurance depends on the insurer having an accurate picture of the building. Anything that changes the risk is something they may want to know. Spray foam on the underside of a pitched roof is such a feature, because it alters how the roof behaves and how a loss might develop.
The insurer's concern is a practical one. Foam can hide leaks, trap moisture against the timbers and make repair harder. A claim for water damage or a failed roof might be investigated more closely if foam is present, and the insurer will want to understand whether the damage came from a sudden event or a long-running problem.
A RICS consumer guide on spray foam appeared in March 2023 and raises the risk of damp building up unseen. Insurers, like lenders, will know of it. For the age side of things, see how long spray foam lasts, which explains what shapes a roof's condition over the years.
Should you declare it?
In our view, yes. We are roofers, not insurance advisers, and we cannot tell you what your policy says. The general principle in insurance is that you give accurate answers to the questions you are asked, and that you take care not to mislead the insurer. If a policy asks whether the property has had alterations or unusual insulation, or if the insurer asks for details of the construction, foam is part of the honest answer.
Failing to mention it risks trouble at the worst time. If you make a claim and the insurer finds that foam was fitted and not disclosed, they may argue that you misrepresented the property. That can lead to a reduced payment or a dispute about the policy. We cannot predict the outcome in any case, but a dispute is a poor time to find out.
The simple route is to phone your insurer or broker, say you have spray foam in the roof, ask if it affects your cover and request their answer in writing. File the reply alongside your other roof papers. If you are unsure of the wording, the Association of British Insurers publishes general guidance at abi.org.uk.
What an insurer may ask you
Questions vary, but they tend to follow the same themes. Having the answers ready makes the call easier.
- When was the foam fitted, and by whom?
- Is it open-cell or closed-cell foam, and how thick is it?
- Do you have installer paperwork, product data and any guarantee?
- Has the roof been inspected since the foam went in, and is there a report?
- Has there been any leak, damp or condensation in the roof space?
- Is the property on the market, or being remortgaged?
If you do not know the answers, a loft inspection can supply some of them. Our page on selling a house with spray foam lists what buyers and surveyors usually look for, which overlaps with what insurers want.
How foam can affect a claim
Many standard policies exclude gradual deterioration and everyday ageing. A Which? article on storm claims makes a similar point about water entering through a poorly maintained roof, which is the kind of loss an insurer may probe where foam is present. That point applies to foam as much as to anything else.
If a slipped slate lets water in and the foam spreads it into the timbers over months, an insurer might argue the damage was gradual. If the roof was inspected recently and found dry, you are in a stronger position. Evidence of condition before an event helps your case, and the lack of it hurts.
Nobody can promise a claim will be paid, and handling claims for customers is not something we do. What we can do is record the condition of your roof with dated photographs and a written note, which you may use as you see fit. Our page on spray foam and a new roof explains how foam affects replacement work, which can matter after a loss.
Cover for the work itself
If you plan to have foam removed or the roof repaired, check whether the work needs to be reported to your insurer. Some policies ask to be told about major alterations or periods when the building is under repair.
Ask the roofer for a written scope and a firm price, and keep the paperwork, because a dated record of the work backs up any later claim or sale. Be wary of anyone who asks you to keep the work from your insurer.
On cost, MyBuilder's 2026 spray foam removal guide reports typical UK removal at about £20 to £50 per square metre, averaging around £1,500. Those are UK-wide figures from a single guide, so treat them as background rather than a quote.
How a roof report helps
A good report records the foam type, the moisture readings on exposed timber, the condition of the covering and flashings, and any signs of leaks. It gives your insurer, lender or buyer a factual basis rather than a guess, and it gives you something dated to point to if a dispute ever arises over when a fault began.
The visit costs nothing and the photographs cover your own roof. We will tell you clearly what we see, including when the roof looks fine. Repairs we carry out come under our written 10-year workmanship guarantee, with the price fixed in writing beforehand.
For the wider subject, return to our spray foam insulation page.