
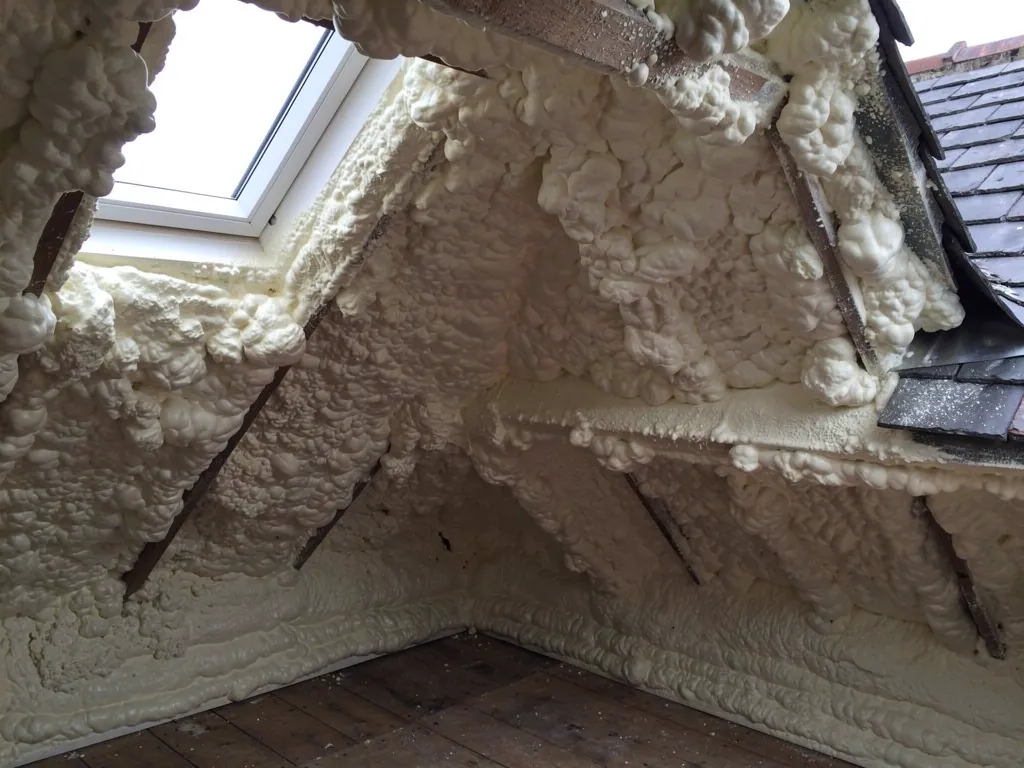
Foam in the roof used to be a selling point. Today it is a line in a survey that can make a buyer pause. A purchaser reads a report that says part of the roof structure is hidden behind insulation, their solicitor asks questions, and their lender may want to know more before it releases the money. For a seller, that can feel like a problem that appeared from nowhere. It helps to see it as a question of evidence. Buyers rarely walk away because foam exists. They hesitate because nobody can say what is behind it. This guide looks at how foam affects a sale, what buyers, surveyors and lenders tend to do, and the realistic options for a seller: selling with the foam in place, having the roof assessed first, or taking the foam out. We are roofers, so we stick to the roof. Your solicitor and estate agent advise on the sale itself.
How foam shows up during a sale
Foam tends to surface at the survey. A surveyor goes into the loft and finds the underside of the roof coated in a hard layer. They cannot see the rafters, the battens or the underlay, so they say so. The report may recommend further investigation, which is the surveyor's way of saying the roof cannot be signed off on sight alone. That recommendation often travels to the buyer's solicitor and the lender in a single email.
From there, three things can follow. The buyer may ask the seller for information: when the foam was installed, by whom, what type, and whether paperwork exists. The buyer may ask for the roof to be inspected by a specialist before exchange. Or the buyer may ask for a lower price to allow for the unknown. None of those is a refusal. Each is a request for information, and a seller who has the information to hand can answer it in days rather than weeks.
The timing matters. Foam is much easier to deal with before a sale is agreed than during one. Once a buyer has instructed a solicitor and a surveyor and paid for searches, delay costs them money, and they may lose confidence. A seller who discovers foam at that stage has less room to manoeuvre than one who finds out when first thinking of moving.
Not every buyer will react in the same way. Some are comfortable with a clear report and a sound roof, while others, particularly those relying on a mortgage, have little choice but to follow what the lender requires. That is why the lender's attitude, covered next, often matters more than the buyer's.
Lenders and mortgage valuations
A buyer who needs a mortgage has to satisfy the lender as well as themselves. The lender's valuer inspects the property, and if the report mentions foam, the lender may apply its own policy to it. Policies are set by each lender and can change, which is why no general answer exists.
The best-known snapshot comes from a BBC investigation reported on 20 November 2024. Some lenders told the programme they would decline such homes, while others said they would weigh each property on its merits. That was a snapshot taken on that date. A lender's position may be different now, so the only reliable step is to ask the lender involved, in writing, and to keep the reply.
The RICS consumer guide of March 2023 adds to the picture by telling owners to ask their lender if its rules permit these products. The guide is written for householders, but it is also read by surveyors and conveyancers, which is why it comes up so often in sales. You can read it on the RICS spray foam consumer guide page, and we explain it in simple language in our page on the RICS position on spray foam.
The consequences for a seller are practical. If a buyer's lender declines, the buyer may have to find another lender, pay cash or withdraw. Cash buyers and buyers with lenders who judge each case are in a better position to proceed. That narrows the field of buyers, which can affect the price and the time on the market. Evidence that the roof is sound, or that the foam has been dealt with, widens the field again.
Your options as a seller
There are broadly four routes, and the choice rests on the roof, the market and how quickly you want to move. None is a requirement.
Sell as it stands
You can market the house with the foam in place and be open about it. This is simplest, and it can work with cash buyers or buyers whose lenders accept foam. It carries risk, because a deal can fall through late if a lender balks. Be ready for questions and price in the possibility.
Commission an assessment first
An independent assessment of the timbers, ventilation and underlay gives you a written record. If the roof is sound, the report is a strong document to hand to buyers and their surveyors. If it shows problems, you learn that before negotiating, not during. Assessments typically run at £100 to £200 in the UK, according to the MyBuilder spray foam removal cost guide (2026).
Remove the foam and re-insulate
Removing foam and fitting conventional insulation takes the issue away altogether. It costs more and takes time, but it changes the conversation with buyers from a risk to a documented repair. What is fitted, and how the roof is ventilated afterwards, is described in our guide to insulating again.
Offer a price adjustment or retention
Some sellers agree a reduction or a retained sum with the buyer, leaving the buyer to deal with the roof after completion. Your solicitor can explain how that works. It transfers the job to the buyer, and some lenders will want the work done before they release funds.
Whichever you choose, we can inspect and report, and the written findings are yours to give to any buyer.
The evidence that helps a sale along
A sale moves faster when questions have documents behind them. If you have foam, build a file before you list or as soon as you decide to sell.
Start with the installation records: the date, the contractor, the invoice, the product data sheets and any guarantee or certificate. Even partial records help. They show what was applied and where. Where nothing survives, an assessment can stand in for the missing records.
Add the assessment report. A good one records the type of foam if it can be identified, the areas covered, the moisture readings, the condition of the timbers and underlay, what ventilation exists at the eaves and ridge, and photographs of each finding. It should be dated and signed by the person who carried it out.
If work has been done, add the removal record, the timber repairs, the new insulation specification and any building control paperwork or completion certificate. A buyer's solicitor looks for these, and a missing certificate can hold up completion.
Include the history of any leaks and repairs. Where a ceiling stain was investigated and cured, a note says so, and the lender sees a roof that has been looked after.
Finally, if you have had a conversation with your own lender or insurer about the foam, keep a copy of their reply. Buyers like to see that the issue has been faced. A tidy folder turns an unknown into a known, and a known is something a buyer can price.
Condensation, insurance and the questions behind them
Buyers who read about foam often ask about two related topics. The first is condensation, because moisture trapped in a sealed roof is the damage mechanism that concerns surveyors. If your house has had no damp problems, say so and give your evidence. If it has, explain what was done. The condensation guide sets out how the problem arises and how it is checked, and it helps a seller to answer a buyer's questions with facts.
The second is insurance. A buyer will want to know whether a policy covers the property with foam in the roof, and what an insurer will say about it. We cannot speak for insurers. Their position depends on the company and the policy wording, so ask yours and keep the answer on file. The home insurance guide covers the points worth raising.
Both topics are easier to deal with when the roof has been inspected. A sound report supports your answer on condensation, and a clear record helps in a conversation with an insurer.
For houses in Bath, one more point applies. Many older properties are listed or in the conservation area, which may affect what can be done to a roof, and the sale of such a house tends to draw a more careful survey. Check with B&NES planning if a roof alteration is on the table.
What you say to a buyer should be accurate and complete. Your solicitor will explain what you must declare on the sale forms, so raise foam with them early and follow their advice.
What it costs and how we help
Costs depend on the roof, and national figures give only the outline. According to the MyBuilder spray foam removal cost guide (2026), removal typically costs £20 to £50 per square metre in the UK, with the average job at about £1,500, and disposal of the removed foam at £150 to £400. The guide lists loft area, the type of foam, the state of the timbers behind it and the insulation and membrane that replace it as the factors that move the total.
For a seller, the cost needs to be set against the value of a smooth sale, and against what a buyer might knock off the price. A seller who removes the foam and fits conventional insulation gets a roof with a clear history. A seller who sells as it stands keeps the money but accepts uncertainty. The right answer depends on your timetable and your appetite for risk, and we give no advice on the sale price.
Our part is the roof. We survey at no charge and photograph the roof in question. A fixed written price then covers whatever you choose to have done, whether that is an assessment, a partial repair or full removal and re-insulation. We clear the site and take waste away, and we provide photographs of the rafters once the foam is off, which a buyer's surveyor can check against the report.
If the timeline is tight, tell us at the start. We cannot promise dates, but we can plan the work in the order that gets the paperwork ready soonest. The whole service is described on our spray foam insulation page.