
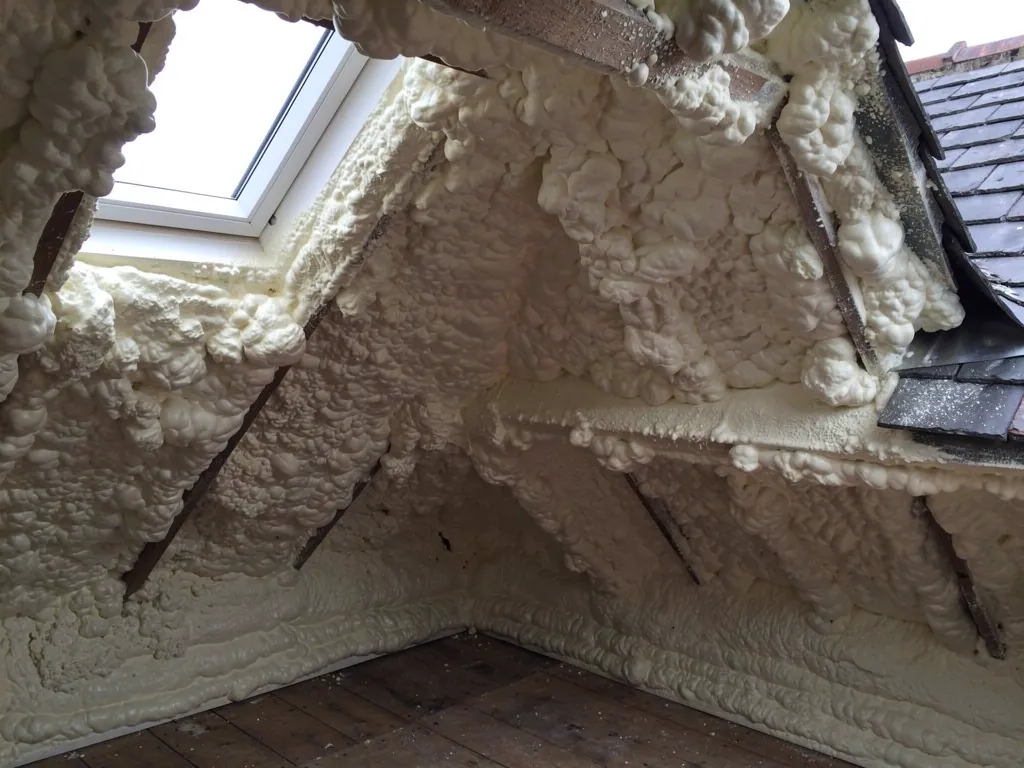
Anyone who has searched for spray foam problems will have met three letters: RICS. The Royal Institution of Chartered Surveyors is the professional body for chartered surveyors, and in March 2023 it issued a consumer guide covering spray foam insulation. Estate agents quote it, conveyancers refer to it and surveyors often mention it in reports. Yet few owners have read it, and secondhand summaries tend to stretch it in both directions. Some say it bans foam outright. Others say it is a routine note that changes nothing. Neither is a fair reading. This page sets out in ordinary language what the guide is, the two points it makes that matter most, what it does not claim, and what a sensible owner does with it. We are roofers, not surveyors, so we describe the guide and the roof evidence side by side, and leave valuations and legal views to the professionals who give them.
What RICS is and why its view carries weight
RICS is a global professional body, and in Britain its members include the chartered surveyors who carry out most home surveys and many mortgage valuations. When a buyer commissions a building survey, the person doing it is very often an RICS member working to RICS standards. That is why a note from RICS is read closely in the property world: it tells surveyors how the body expects them to treat a topic, and it tells consumers what to ask.
The body does not write law, and it does not regulate lenders. A RICS consumer guide is advice. It has no power to forbid anyone from installing foam or to oblige anyone to take it out. Its force comes from how the people who rely on it behave. Surveyors who follow it will flag foam in reports. Valuers who follow it will raise questions. Lenders who follow it may add their own conditions. Each of those steps is taken by someone else, using their own judgement.
It also matters what kind of document this is. A consumer guide is written for householders, not for technical specialists, so it speaks in broad terms and avoids the detail of a particular roof. It cannot tell you whether the rafters over your landing are dry or whether your slates are nailed sound. It was never meant to. That detail is the job of an inspection, and it is the reason a guide and a roof assessment complement each other rather than compete.
Keep this in mind throughout. The guide frames the questions. The roof supplies the answers.
What the March 2023 guide says
The RICS consumer guide on spray foam insulation was published in March 2023. The full text is on the RICS spray foam consumer guide page, and it is short enough to read in one sitting. Two messages in it matter most to a roof owner.
The condensation and damage warning
The guide cautions that condensation can get out of control and harm parts of the building. In roof terms, that is the concern we meet on site. A pitched roof normally manages moisture by letting air pass through it. When foam is applied under the covering and across the rafters, that movement can be cut off. If household moisture reaches cold surfaces, it condenses, and in a sealed build-up there may be nowhere for it to go. The risk lands on the timber, the underlay and the nails. Our guide to inspecting roof timbers under spray foam describes how that is checked.
The advice to speak to your mortgage provider
The guide also tells owners to ask their lender whether its own rules permit these products. Read the wording closely. The lender's own policy is the thing to check, not an assumption. Policies differ from one lender to another and can change.
Those two messages are the core. Everything else that gets attributed to the guide is interpretation, and interpretation is where the confusion starts.
What the guide does not say
We read the guide as a caution, not a verdict. It does not say that every foamed roof is failing. It does not say that foam must come out of every house. We have not seen it describe a timber moisture level that triggers removal, a date after which foam becomes unacceptable or a standard for a good installation. It leaves those questions open because they depend on the roof, the foam and the ventilation, and no consumer guide can settle them.
That caution matters, because two tempting shortcuts both mislead. The first is panic: assuming the guide means your roof is condemned. Foam over a dry, sound, well-detailed roof may cause no trouble at all, and a spray foam assessment can show that. The second is dismissal: assuming the guide is only about newer installations or has no bearing on your sale. Surveyors and buyers do read it, and a lender may have its own stance that is stricter than the guide.
Nor does the guide settle who is to blame if something went wrong. Whether foam was mis-sold, wrongly installed or simply unsuited to an older roof is a separate matter, and for questions like that you would turn to the installer's paperwork and, where needed, to advice on your consumer rights. Our page on spray foam that was mis-sold looks at the points to gather.
So treat the document as the start of a conversation with your surveyor and lender, not the end of one. We keep to the same reading in our own work: the guide raises a concern, and the roof tells us whether the concern applies.
How surveyors, buyers and lenders use it
In practice, the guide shows up at three moments.
The first is a survey. A surveyor who finds foam in a loft may mention it in the report, note that the wood behind it is hidden and suggest further investigation by a specialist. That is a cautious thing to do, and the guide supports it. A report of that kind does not state that the roof is defective. It says the roof cannot be fully assessed.
The second is a purchase. A buyer who has read about foam may ask the seller questions, ask for any paperwork and ask to see evidence of the roof's condition. If the seller has no answers, the sale can slow down or the price can come under pressure. The page on insulating again once foam has gone is relevant here, because a finished re-insulation with paperwork is a strong answer to the question.
The third is a loan. Lenders set their own policies. A BBC investigation reported on 20 November 2024 heard from some lenders that they would turn down such homes, while others said each case is judged separately. That position can change, so it should be checked afresh with whichever lender is involved. We do not name lenders here, because the policy is theirs to state. The lending side gets fuller treatment in our mortgage guide.
In each case, the key to a smooth outcome is evidence. A surveyor can work with a written assessment of the timbers, a record of the ventilation and, where foam has been removed, a note of what replaced it. A vague history is what slows things down.
What a sensible owner does with it
First, establish what is in the roof. Look through the paperwork from the installation for the date, the installer, the type of foam (open-cell or closed-cell), the areas covered and any guarantee. If the paperwork is missing, say so openly to anyone who asks, and rely on an assessment to fill the gap.
Next, ask the right person the right question. If you are about to buy or refinance, speak to your mortgage provider, as the guide advises, and ask in writing what their position is on foam. If you are thinking of installing it, speak to the lender before you sign the contract, not after, and ask your surveyor whether the roof you have is a good candidate for it.
Then get the roof looked at. The cleanest answer to a guide that raises a concern is a person on site who can report on the timbers, the nails, the underlay, the eaves and the ventilation. We carry out that assessment and give you a written report with photographs of your own roof. The survey is free, and the report is yours to hand to a surveyor, a buyer or a lender.
Finally, decide about the foam on the evidence. Where the timbers are sound and the ventilation is workable, leaving it in place may be reasonable. Where there is damp wood, blocked eaves or a lender that will not proceed, removal and re-insulation is a practical route. Keep all the paperwork together as you go. A complete file turns a worrying phrase in a survey into a settled point.
What the guide means for the roof itself
Because the guide is about condensation and damage, the physical questions it raises are all questions about the roof. Is the timber dry? Does the eaves ventilation still work? Is the underlay intact? Are the nails sound? Are the slates held in place without foam gripping them? None of those can be answered from a desk, and each can be answered by an inspection.
If the answers are good, the roof may be left as it is, with the evidence on file. If they are mixed, a partial approach can work: opening up and repairing the affected areas, then restoring ventilation where it has been lost. If they are poor, removal followed by correct insulation and ventilation gives a roof that behaves the way a conventional one does. Each of those routes is a decision for you, guided by the survey and by what your lender will accept, and none is forced by the guide.
For older houses in and around Bath, there is a further point. Many are built with stone walls, timber roofs and lime-based materials that were designed to let moisture move. Sealing a roof with a material that does not let it move is a mismatch of building physics, and an older building is less forgiving of that mismatch than a modern one. That is a reason to take the guide's warning seriously on a period house, without assuming the worst for yours.
Should you want the roof assessed, a spray foam assessment typically costs £100 to £200 in the UK, according to the MyBuilder spray foam removal cost guide (2026). Ask the assessor to record the condition of the rafters behind the foam, with photographs, because a lender's valuer usually wants to know whether the timber can breathe. The whole process is set out on the spray foam insulation hub.