
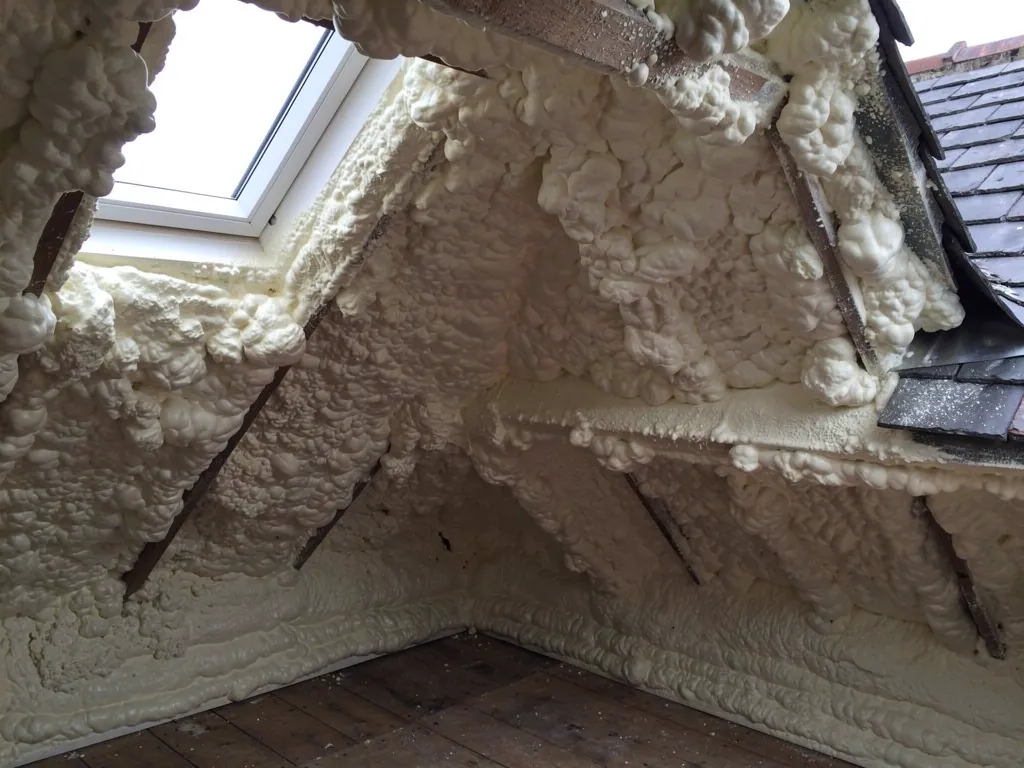
A layer of foam applied under the roof has turned into a question that can hold up a sale or a remortgage. The foam itself is not illegal, and many homes carry it without any trouble. The difficulty is that it hides the timber frame and the reverse of the slates or tiles, which are the parts a surveyor would normally inspect to judge whether a roof is sound. When a lender cannot see the timbers, it has to decide how much risk it is prepared to carry. Policies differ between lenders, and they change. This guide explains the reasoning behind that caution, what was reported about lenders in late 2024, what the RICS consumer guide recommends, and which pieces of roof evidence tend to answer a surveyor's questions. We are roofers and not mortgage advisers, so none of this replaces advice from your broker or solicitor. It is here to help you gather the right facts. Our spray foam insulation service page covers what we can inspect and do on the roof.
Why lenders look twice at a foamed roof
A mortgage is secured on the building, so a lender wants confidence that the structure will keep its value. The roof timbers are part of that structure. If they decay, the repair can be costly and the roof can lose its ability to carry the covering.
Spray foam complicates the picture because it is applied to the inside face of the roof and sticks to what it touches. A surveyor standing in the loft sees a continuous layer of foam where they would usually see bare timber and the reverse of the covering. They cannot look at the wood. They cannot run a moisture meter against it in the usual way, and they cannot see whether a nail has rusted or a slate has slipped behind the foam.
That hidden condition is the root of the caution. It is not that foam must cause damage, but that nobody can easily confirm it has not. The concern most often raised is moisture: if damp air or a small leak reaches timber that is sealed in foam, the wood may be unable to dry out. A lender cannot measure that risk from a valuation visit, so some treat it as a reason to decline or to ask for more evidence.
Two parts of the picture are worth separating. One is the foam as a product, with its type and thickness. The other is the installation, meaning how the roof was prepared, how well it was ventilated beforehand and what was done around the eaves. Lenders rarely see either. The paperwork that would explain both is often missing, especially if the foam was installed by a previous owner.
What the RICS guide says, and what was reported about lenders
In March 2023 RICS issued a consumer guide on foam applied to roofs and walls. It cautions about condensation that is not controlled and about damage elsewhere in the building, and it advises homeowners to ask their mortgage provider, before any installation, whether the lender's policy permits it. The guide is available on the RICS consumer guide page.
Lender behaviour is a separate matter, and it is not set by RICS. Coverage dated 20 November 2024 described a BBC investigation in which a number of high-street lenders said they would decline such houses, while the rest told reporters they weigh each application on its merits. The names were published at the time. We do not repeat the names here, because lender policy moves and a list that was accurate then may not be now. The useful lesson is that two lenders can treat the same house differently, and one lender can treat two houses differently depending on the evidence.
Because that position is reported rather than fixed, treat it as a prompt to ask questions early, not as a statement of today's policy. Ask your broker or the lender's underwriting team, in writing, what they require when a house has foam under the roof. Ask whether the answer depends on the foam type, the area covered, or whether a specialist report is needed. Keep the reply.
How a surveyor approaches foam in the loft
A chartered surveyor writing a report on a house will usually note insulation they can see and any limits on what they could inspect. If the roof space has foam over the timbers, the report is likely to say so and to say that the structure behind it could not be examined. A cautious surveyor may go further and recommend that a specialist inspect the roof timbers before the purchase goes ahead.
That recommendation is where a roofer comes in, but the surveyor and the lender decide what they accept. Our job is to supply facts. We cannot promise that a lender will lend because a roofer has looked. We can make sure the person reading your file sees clear photographs, a short description of what was opened up and an honest note of what could not be reached.
Several points tend to shape the surveyor's view of a given loft. The first is extent. A small patch of foam over a bathroom extension is a different question from a roof where every rafter bay has been filled. The second is the age and type of roof. A recent roof with a modern breathable membrane behaves differently from an old slate roof laid without one. The third is visible evidence of trouble elsewhere, such as stained ceilings, mould in the eaves or slipped slates seen from outside.
On older Bath houses, with lime-pointed stacks, lead-lined gutters and timbers that have been in place for a long time, surveyors tend to be careful about anything that stops air moving through the roof. The point is not to alarm you but to explain why a report on a period house may ask for more than a report on a newer one.
The roof evidence that helps
When a lender or surveyor hesitates, evidence is what moves things. The most useful pieces are factual and specific.
Installation records
Look for the installer's invoice, the product name, the date and any guarantee or data sheet. Records tell a surveyor what is in the roof, and a named product is easier to assess than an unknown one. If the previous owner had the work done, the solicitor may be able to request the papers.
A timber inspection
Where foam can be opened up safely in places, a roofer can check the rafters and battens beneath it, take moisture readings and photograph what is there. The report should say where the foam was opened, what was found and what could not be seen. We describe what the inspection involves on our page about spray foam and roof timbers.
Condition of the roof outside
A sound covering, intact lead at the chimney and valleys, and working gutters all reduce the chance that water is reaching the foam. A roof survey with photographs of the external condition belongs in the same file.
Ventilation and signs of condensation
A note on whether the eaves are clear, whether there is any staining and whether the roof space smells damp gives a surveyor a picture of how the roof behaves in use. Our guide to the spray foam survey describes how we gather it.
Foam type, and why a lender asks about it
Lenders and surveyors often ask which type of foam is in the roof, because the two behave differently around timber. Open-cell foam is soft and lets moisture vapour pass more readily. The closed-cell type is hard and slower to let vapour through. Neither type is automatically accepted or rejected by every lender, but a report that names the type is more use than one that says only "spray foam".
Identifying the type from the loft is not always easy. Colour and feel can mislead, and foams that look alike can behave differently. The records help, and so does a trained look at a small sample of the foam where it has been cut. Our comparison of the two foam types sets out the difference and why it matters for roof timbers.
It is also worth saying what a type name does not tell you. Two roofs with the same type of foam can be in very different condition, because ventilation, the quality of the original roof and any leaks all play a part. A lender who sees only the type may still want evidence about the timbers. That is why the inspection and the photographs carry more weight than a label.
If a lender says no: the options
A refusal is not the end of the road, but it changes the plan. The usual routes are these.
The first is to supply evidence and ask the lender to reconsider. A timber report, installation records and a clear photographic record of the roof sometimes change a lender's answer. Ask what exactly it needs, and do not assume a general statement of policy is the final word on your property.
The second is to try another lender, which a broker can do. Because policies differ, a case refused by one lender may be considered by another.
The third is to take the foam out, in whole or in part. Taking it out lets the timbers be inspected and, if they are sound, the roof can be re-insulated with something a lender is happy to see. This is a real cost, and it takes time, so compare it with the alternatives before committing. Our guides on what spray foam removal costs and on whether to remove spray foam help you weigh that choice. Removal is not the only answer, and it is not always the right one. Where the roof has no problems and a lender would accept evidence, leaving the foam may be sensible.
If you are buying, speak to your solicitor before exchange. If you are selling, gathering the evidence before a buyer asks can save weeks of back and forth. Whichever route you pick, a roofer's written findings give everyone the same facts to work from. We can supply those findings for a house in Bath or the surrounding area, backed by pictures of the roof and, for any work that follows, a written fixed price after the survey.