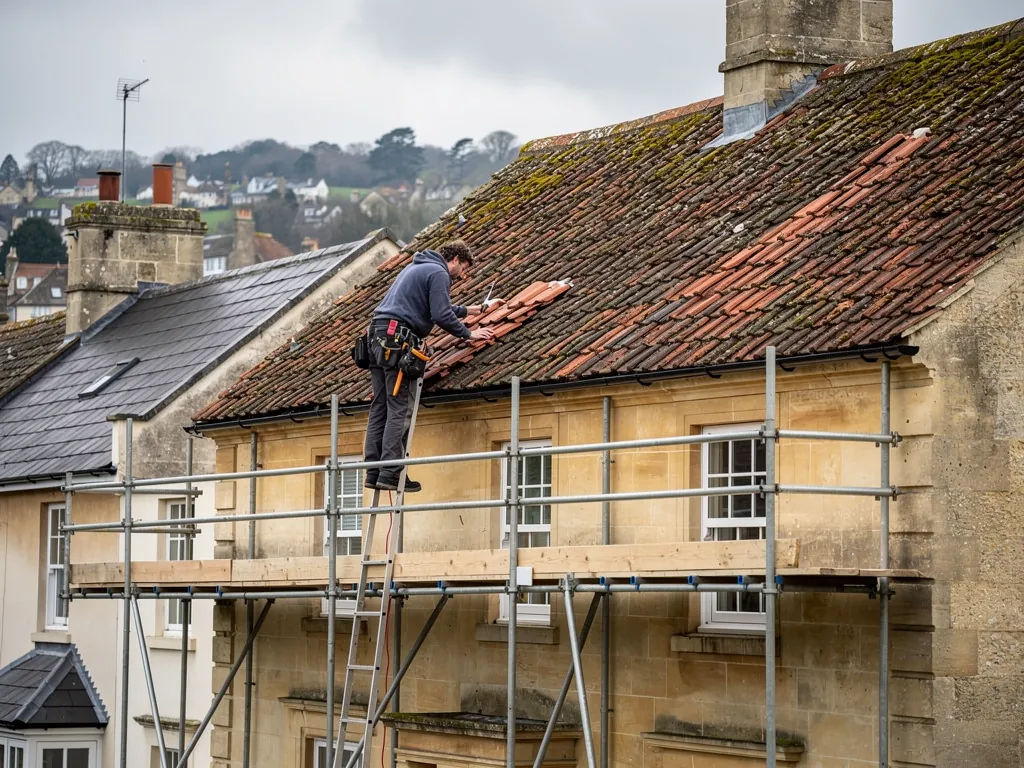
The short answer
An insurer may pay for slipped tiles when a storm caused them, but a standard policy commonly excludes wear and tear. Many insurers treat gusts of at least 55 mph as a storm. If the fixings had already failed, the claim is more likely to be refused. Photographs, dates and a roofer's written report on the cause give your claim its best chance, though nothing guarantees an outcome.
The line between storm damage and wear and tear
A home policy reads like a list of events. It pays for sudden damage from a named cause, and a storm sits on that list. It does not usually cover the slow loss of condition every roof goes through. Slipped tile claims are won or lost in that gap.
What counts as a storm is set out in your policy wording. A common yardstick comes from the Association of British Insurers, whose storm definition features gusts of 55 mph or more. Which? warns that ordinary policies may leave out general wear and tear, and gives rain getting in through a poorly kept roof as an example. In a piece from November 2025 it quoted Financial Conduct Authority data: just 32 per cent of storm claims made in 2024 ended in a payout.
Those figures say nothing about your own claim, but they explain why evidence matters. A tile that slips in a named storm after years of good condition is a very different claim from a tile that slips on a calm day because the nail has rusted.
Why tiles slip, and why it matters to a claim
A tile stays on a roof because of its weight, its nibs or hooks that engage the batten, and in many cases a nail or clip. Anything that undermines one of these lets it move. Wind lift is the obvious cause, and it is why storm damage is common after a gale. But there are quieter causes that insurers regard as maintenance.
Nails can corrode. Battens can rot and lose their hold, and mortar under a ridge or hip can crumble. A tile can also drop where the roof has been walked on or where the pitch is too shallow for the product. Our guide on why tiles slip goes through each cause in turn.
For a claim, the cause is the whole case. If the slipped tiles are scattered, clustered on the windward slope and the neighbours lost tiles too, the case for wind is strong. If they run along one slope, sitting on rotten battens, the insurer may see a maintenance failure. Roofers meet both kinds. Our part is to describe what we find without trade jargon and to show it in pictures, with no verdict on cover, which is the insurer's call.
What an insurer will want to see
An assessor will normally ask for the following, and gathering it early saves time.
- The date of the weather. Note when you noticed the damage and what the weather was doing. Local weather reports for that day are useful.
- Photographs. Shoot from the ground, or from a window you can reach safely. Stay off the roof itself.
- A written account of the fault. A short report from a roofer saying what slipped, what the battens and nails look like and what the likely cause was.
- Proof of condition. Earlier photographs, past repair invoices or a survey show the roof was in order beforehand.
- Quotes. Insurers often want a repair estimate before they agree to pay.
Keep damaged tiles and nails if you can. Do not throw away the evidence on the day of the repair. A fallen tile in the garden is worth photographing where it landed, because direction and distance from the house hint at the wind.
Timing helps too. Report promptly, because a delay lets an insurer argue that the damage worsened through neglect. Read the policy for any excess, the sum you pay towards a claim, since a cheap repair of a few tiles may cost less than the excess. In that case a claim may not be worth making, and the money is better spent on a lasting fix.
What happened in a real dispute
The Financial Ombudsman Service publishes anonymised case studies, and one involves an insurer that refused a storm claim for tiles blown off a roof. The ombudsman did not insist on a wind-speed reading. It relied on local weather reports, judged that wind had been the chief reason for the tiles coming off, and pointed out that the policy's wear-and-tear exclusion extended only to accidental damage. The case study is worth reading in full.
It is one case, decided on its facts and the wording of that policy, so do not read it as a rule. It does show that an insurer's first answer is not always the last word, and that evidence on the cause of the damage counts for a great deal.
We cannot handle a claim for you, and nobody can promise one will succeed. What we can offer is a clear account of the roof as we find it.
Repair first, claim carefully
A claim takes time, and the roof cannot stay open to the weather meanwhile. Many policies ask you to limit further harm, and every wet week enlarges the loss. A temporary repair to stop a leak is normal practice, but keep the receipts and photographs, and check your policy or ask the insurer before committing to the full repair.
When slipped tiles are only part of a larger problem, such as a worn roof or sagging battens, the sensible plan is to separate the two. The storm-related repair can be described, and the wider wear dealt with as maintenance. Where tiles are old or the roof is listed, you may need matched or reclaimed replacements, and our page on reclaimed roof tiles covers how to find them.
Also check the loft. Condensation can stain timber and make it look as if the roof leaks, so read our page on loft condensation before you describe a stain to an insurer. Frost can also break tiles over several winters, which is wear, not a storm: see frost-damaged tiles. For the wider picture on roof coverings, the pitched roofing page is the place to start.