The short answer
Yes, spray foam can stop an equity release application. As of 20 November 2024, a BBC investigation reported that Aviva said it would not offer equity release on homes with spray foam. Other providers may assess each case. Foam in the roof is often raised by the valuer, so check with an adviser before applying and keep your records ready.
Why equity release providers look hard at foam
Equity release lends against the value of your home, and the loan is usually repaid when you die or move into long-term care. The lender therefore needs to be confident that the house will keep its value for many years, and that it can be sold when the time comes.
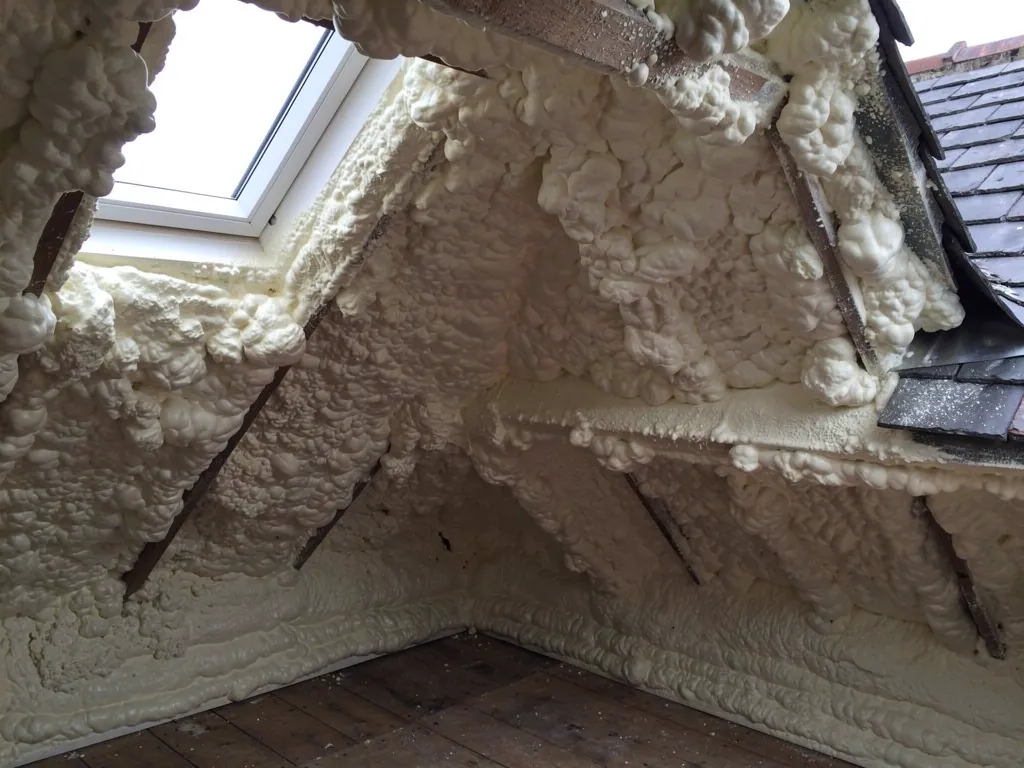
That is where spray foam causes trouble. Foam applied beneath a pitched roof can hide timber decay, trap moisture and make the roof hard to repair. RICS published its spray foam consumer guide in March 2023. It flags the risk of damp building up and harming the property, and it urges anyone with a mortgage to check the lender's own rules on foam first. A valuer who spots foam in a loft will often report it, and the provider then decides whether to proceed.
The concern is about resale and structure, not about you. A home that is hard to sell weakens the provider's security. For you, the practical result can be a refusal, a delay or a request for more evidence.
What has been reported about lenders
Lender positions are best treated as a snapshot. A BBC investigation, reported on 20 November 2024, said TSB, Skipton, the Co-operative Bank, Principality and Aviva (for equity release) would decline a home with spray foam insulation. It also said Lloyds, Nationwide, Barclays, NatWest Group and Santander assess case by case.
That was a point in time. Policies change, and providers often differ in how they treat different foam types, roof types and evidence. Some lenders have declined, while others look at the specifics, so it is wrong to assume either that every provider will refuse or that all will accept.
For equity release in particular, ask a regulated adviser which providers are currently willing to consider a home with foam, and ask the adviser to check before you pay for a valuation. A refused application can leave a note against the property that you would rather avoid. Our page on spray foam and mortgages covers the wider lending picture.
What evidence tends to help
Where a provider will consider foam, it usually wants proof that the roof is sound. The more of the following you can supply, the stronger your case.
- A roof inspection report. Moisture readings on accessible timbers, photographs and a written opinion on the condition of the roof structure.
- Installer paperwork. Product data, the date of installation, the installer's name and any guarantee, ideally with a note on how ventilation was handled.
- A surveyor's view. A chartered surveyor who has seen the loft and reports on the foam is more persuasive than a general statement.
- Condition of the covering. A sound slate or tile covering with no history of leaks supports the case that nothing is hidden.
Be wary of anyone who promises that their report will satisfy a lender. We cannot speak for providers, and a report only helps if the roof is genuinely in good order. Our page on spray foam and roof timbers explains what we check when we assess the structure.
If the application is refused
Being refused does not close every door, though your choices depend on what the roof shows.
The first option is to try another provider. Some are more willing to look at foam with evidence, and an adviser will know which. The second is to remove the foam, check and repair the timbers, and re-insulate with a breathable material, then apply again with a report showing the work. That route costs money, but it can restore your options. The third is to leave the home as it is and look at other ways of raising funds, which is a conversation for a financial adviser rather than a roofer.
If removal is on the table, UK cost guides give a rough idea. MyBuilder's 2026 spray foam removal guide lists £20 to £50 per square metre, about £1,500 on average. That is a general UK picture rather than our price, and ours is worked out once we have seen the loft for ourselves. Doing the work yourself can leave a lender with no evidence, so see removing spray foam yourself before you try.
Was the foam sold to you wrongly?
Some owners find out about the problem only when an application fails, long after the foam went in. If you were told that foam would raise your home's value, or that it would have no effect on a mortgage, you may have grounds for a complaint. If so, what to do if spray foam was mis-sold explains where to begin.
Gather your paperwork before you do anything else: the quote, the contract, any marketing material, product details and photographs of the loft. The older the installation, the harder it is to piece the story together, so do not wait.
Where we fit in
We are roofers, not financial advisers, and we do not speak for any lender. What we can do is look at the roof, say whether the foam is hiding a problem and tell you what a repair or removal would involve. The visit is free of charge, the pictures we take show your own roof, and any work is priced firmly in writing. We will also tell you up front if we think the foam can safely stay, because a needless removal helps nobody.
For the full picture of the subject, go to our spray foam insulation page.